
By Dylan Serna, ADU Realtor (DRE #02217359), eXp Realty · Long Beach and Orange County · Last updated October 27, 2026
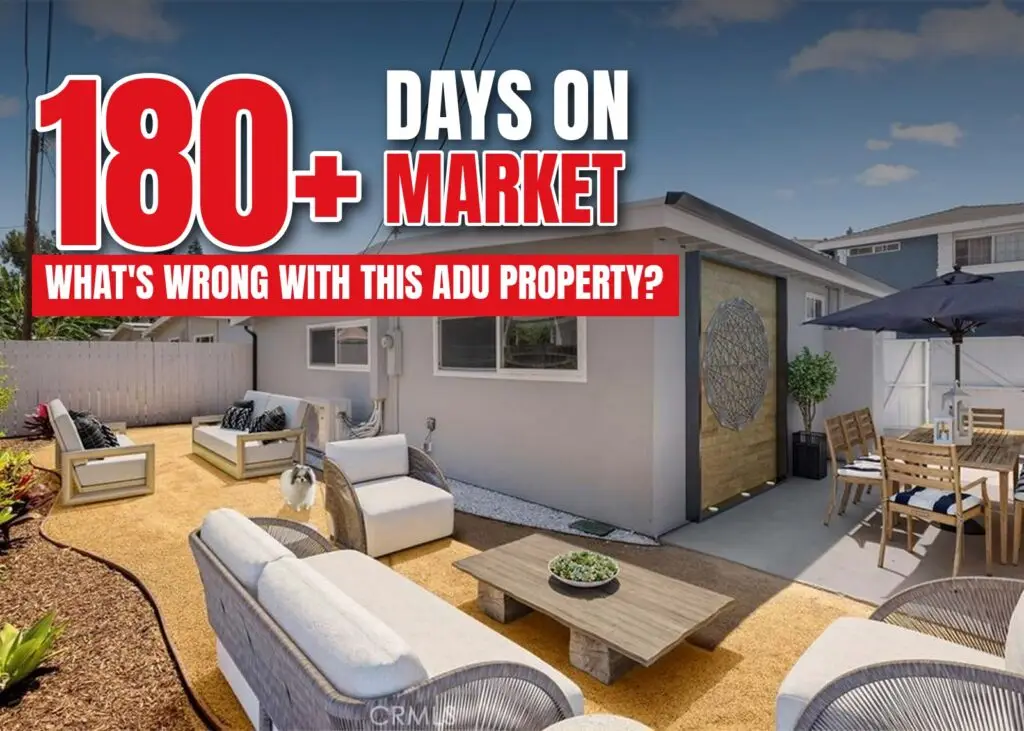
Your listing expired, or it’s been sitting for 60+ days with a couple of showings and no offers. You have an ADU, which is supposed to be the selling point. So what happened?
The short answer: when a Long Beach home with an ADU doesn’t sell, it’s almost always one of three things. It was priced as if the ADU added more than the comps support, the ADU’s permits or paperwork scared off lenders and appraisers, or the listing never showed buyers the rent numbers they need at 7%+ rates. All three are fixable before you relist.
Key Takeaways
- The market changed under you. Long Beach multi-units hit 6.63 months of inventory in September 2026, a buyer’s market. Overpriced listings sit. Fairly priced ones still close near 98% of list.
- An ADU only adds value an appraiser can see. No permit, no final sign-off, or no ADU comps usually means they add a limited amount of value in comparison to a permitted one.
- Buyers buy the numbers. At 7.32% rates, investors and house hackers want a signed lease, rent history and a payment-vs-rent breakdown before they’ll write an offer.
What the Long Beach Market Looks Like Right Now
Look at the conditions you listed into. Here’s the Long Beach multi-unit market (the category most ADU properties compete in) as of September 2026:
| Metric | September 2026 | What it means for sellers |
|---|---|---|
| Months of inventory | 6.63 | Over 6 months = buyer’s market |
| Active listings | 232 (up 15.4%) | More competition for every buyer |
| New listings vs. new escrows | 71 vs. 21 | About 3 new listings for every new deal |
| Sold-to-list price | 98% | Priced right still sells near asking |
| Median list price: in escrow vs. still active | $1,100,000 vs. $1,590,000 | Lower-priced listings are the ones selling |
| Days on market: in escrow vs. still active | 36 vs. 64 | Good listings move in about 5 weeks |
Source: RPR Market Trends, Long Beach, CA, Multifamily/Multiplex, September 2026. Full breakdown in Is Long Beach a Buyer’s or Seller’s Market for Multi-Units?
Add rates on top. The 30-year fixed averaged 7.32% on October 22, 2026, per Freddie Mac, up from the low 6s a year ago. Fewer buyers qualify, and the ones who do are running every number. That’s the backdrop for all three reasons below.
Reason #1: It Was Priced Like the ADU Was Worth More Than the Comps Say
This is the most common reason by far. Sellers (and plenty of agents) price an ADU home one of three wrong ways:
- House value + build cost. “The house is worth $850K and the ADU cost $300K, so list at $1.15M.” Buyers don’t pay for your cost. They pay for what the market shows.
- Pricing it like a duplex. An SFR with an ADU is still a one-unit property for financing. It competes with duplexes on income, but it doesn’t always trade at duplex prices.
- Pricing off 2022 comps. Long Beach values have moved sideways since 2022. Listings priced off peak-era sales are the ones still on the market.
Appraisers don’t simply add the ADU’s square footage to the house. Under Fannie Mae’s appraisal guidelines, the ADU gets its own adjustment, and the appraiser has to support it with market data. Freddie Mac’s ADU appraisal guidance says the same thing. So if your list price assumes more ADU value than nearby ADU sales prove, buyers’ lenders won’t fund the gap, and buyers know it.
The fix
- Pull closed sales from the last 6 months with permitted ADUs in your part of Long Beach (North Long Beach, Bixby Knolls, Los Altos and the East Side all price differently).
- Pull similar homes without ADUs to set the baseline for the main house.
- Check the active listings you’re competing with and price below the ones that have been sitting 60+ days.
- Relist at a price the comp package can defend to an appraiser.
Reason #2: The ADU’s Permits or Paperwork Raised Red Flags
Long Beach has a lot of older garage conversions and back houses with thin or missing permit history. If your ADU is one of them, or if the paperwork just isn’t organized, here’s what happens behind the scenes:
- The buyer’s agent pulls permit history and finds a gap. The buyer gets nervous or asks for a big credit.
- The appraiser gives the unpermitted unit less value than a permitted one, so the appraisal comes in short of a price based on legal-ADU comps.
- The lender won’t count the ADU’s rent toward the buyer’s income, so the buyer no longer qualifies.
- Your buyer pool shrinks to mostly cash buyers and investors, who want a discount.
Another Long Beach wrinkle: the city’s old ADU rules (LBMC 21.51.276) are still printed online, but the city says they no longer apply. Every ADU is reviewed under state law, per the city’s ADU bulletin IB-PZ-001. Listing remarks that quote the old rules, or that overstate what the lot can add, confuse buyers.
The fix
If the ADU is permitted, put the building permit, final inspection and certificate of occupancy in the listing documents on day one. Don’t make buyers ask.
If it isn’t, you have three choices: legalize it, sell as-is and price to the as-is comps, or convert it back. AB 2533 lets units built before 2020 be legalized by fixing health and safety issues rather than meeting every current code. Long Beach also has an amnesty program, but it requires a 10-year affordable rent covenant, which most buyers will discount heavily. I compare the paths in How to Legalize an Unpermitted ADU in Long Beach and Selling a Long Beach Home With an Unpermitted Garage Conversion.
Whatever you choose, disclose it clearly. California’s Transfer Disclosure Statement requires it, and a buyer who finds a surprise in escrow is a buyer who cancels.
Reason #3: The Listing Never Showed Buyers the Rent Numbers
The people who pay the most for a Long Beach ADU property are house hackers, investors and multigenerational families. The first two decide with a calculator. If your listing says “bonus ADU, great income potential” and nothing else, they move on to the one that shows the math.
Here’s the kind of breakdown a buyer is running on a $1,100,000 Long Beach home with a 2-bed ADU. It’s illustrative; your taxes, insurance and rents will differ.
| Monthly | 25% down | 50% down |
|---|---|---|
| Loan amount | $825,000 | $550,000 |
| Principal and interest at 7.32% | $5,667 | $3,778 |
| Property tax (about 1.2%) + insurance | $1,300 | $1,300 |
| Total payment (PITI) | $6,967 | $5,078 |
| Rent: main house + 2-bed ADU ($3,500 + $2,900) | $6,400 | $6,400 |
| Monthly cash flow (investor) | −$567 | +$1,322 |
| Share of payment the ADU covers (house hacker) | 42% | 57% |
That table tells a buyer exactly who your home works for. A house hacker sees the ADU covering roughly 40% to 60% of the payment. An investor with 25% down sees a small negative that could still make sense as an appreciation hold, and one with closer to 50% down sees cash flow. ADU rent figures come from my ADU rent by city research.
Rent documentation also helps buyers qualify. Since March 2026, Fannie Mae’s Desktop Underwriter can count ADU rent toward up to 30% of a buyer’s qualifying income on a one-unit primary home (Pennymac Announcement 26-29). That only works with a legal unit and documented rent.
The tenant problem
Tenants cause the other half of these stalled listings: showings that keep getting canceled, an ADU that photographs poorly, or buyers who don’t know if they can move family in. Before you ask a tenant to leave, know the rules. Statewide just-cause law (Civil Code 1946.2) may apply, and Long Beach has its own relocation requirements, listed on the city’s tenant and landlord resources page. Often the better move is to keep a paying tenant and market directly to investors.
The fix
- Put the signed lease, 12 months of rent deposits and the utility setup in the listing documents.
- Add a one-page payment-vs-rent sheet like the table above.
- Shoot the ADU as its own listing: entry, kitchen, bath and private yard.
- Write the remarks for the buyer types who pay the most, not “bonus unit.”
Quick Diagnosis: Which Reason Is Yours?
| What happened | Most likely reason | First fix |
|---|---|---|
| Few showings, no offers | #1 Pricing | Reprice to permitted ADU comps |
| Showings, but buyers went quiet after disclosures | #2 Permits | Organize permits or price as-is |
| Got an offer, then the appraisal came in low | #1 or #2 | Comp package and permit docs to the appraiser |
| Lots of interest from “looky-loos,” no serious offers | #3 Numbers | Add rent file and payment-vs-rent sheet |
| Showings kept getting canceled | #3 Tenant | Set a showing plan or market tenant-occupied to investors |
Should You Relist, Wait or Sell Off-Market?
- Relist if you can fix the reason it didn’t sell. A fresh listing with a new price, a rent file and new photos often gets a second look from buyers who passed.
- Wait if you don’t need to sell and the ADU is rented. Long Beach inventory has swung between balanced and buyer’s every year since 2022, and it usually tightens in late winter and spring.
- Sell off-market if you’d rather not deal with showings and tenants. I keep a list of active Long Beach investors. See Sell Your Long Beach Duplex Off-Market.
For the full step-by-step, read my Long Beach ADU seller’s guide, my Long Beach ADU page, or, if you also own in Orange County, Why Your ADU Property Isn’t Selling in Orange County. Nearby in Lakewood, the same three issues show up.
FAQ
Why is my house with an ADU not selling in Long Beach?
Usually because it’s priced above what permitted ADU comps support, the ADU has permit or disclosure issues, or the listing doesn’t show buyers the rent and payment numbers. With 6.63 months of inventory, buyers have options.
How long should a Long Beach ADU home take to sell?
Well-priced Long Beach multi-unit listings went into escrow in a median of 36 days in September 2026. If you’re past 60 days with no offers, something needs to change.
Does an unpermitted ADU hurt my sale?
Yes. Appraisers usually give it less value than a permitted ADU, lenders won’t count its rent, and your buyer pool shrinks to cash buyers who want a discount. Legalizing under AB 2533 or pricing as-is are the main options.
Should I lower my price or take it off the market?
If you need to sell, reprice to the comps and fix the paperwork. If you don’t, and the ADU is rented, waiting for spring is reasonable. Off-market to an investor is a third option.
Is it better to sell with the ADU tenant in place?
For investors and house hackers, yes, a paying tenant is proof of income. For families moving relatives in, vacant sells better. Check just-cause and Long Beach relocation rules first.
Your listing didn’t fail because you have an ADU. It failed because the price, the paperwork or the numbers didn’t match what today’s buyers need. Send me the address and I’ll tell you which one it was and what I’d change before relisting.
👉 Book a seller consult call to go through your options with Dylan
Prefer to talk now? Call Dylan Serna, ADU Realtor at 714-860-2868.
Dylan Serna | The ADU Realtor | eXp Realty | DRE #02217359
Market data from RPR Market Trends, Long Beach, CA, Multifamily/Multiplex, September 2026, deemed reliable but not guaranteed. Payment example is illustrative and uses a 30-year fixed loan; taxes, insurance and rents vary. Not legal, tax or financial advice.